Categories
Buying a homePublished September 6, 2026
Figuring Out How Much House You Can Afford in Texas City, TX

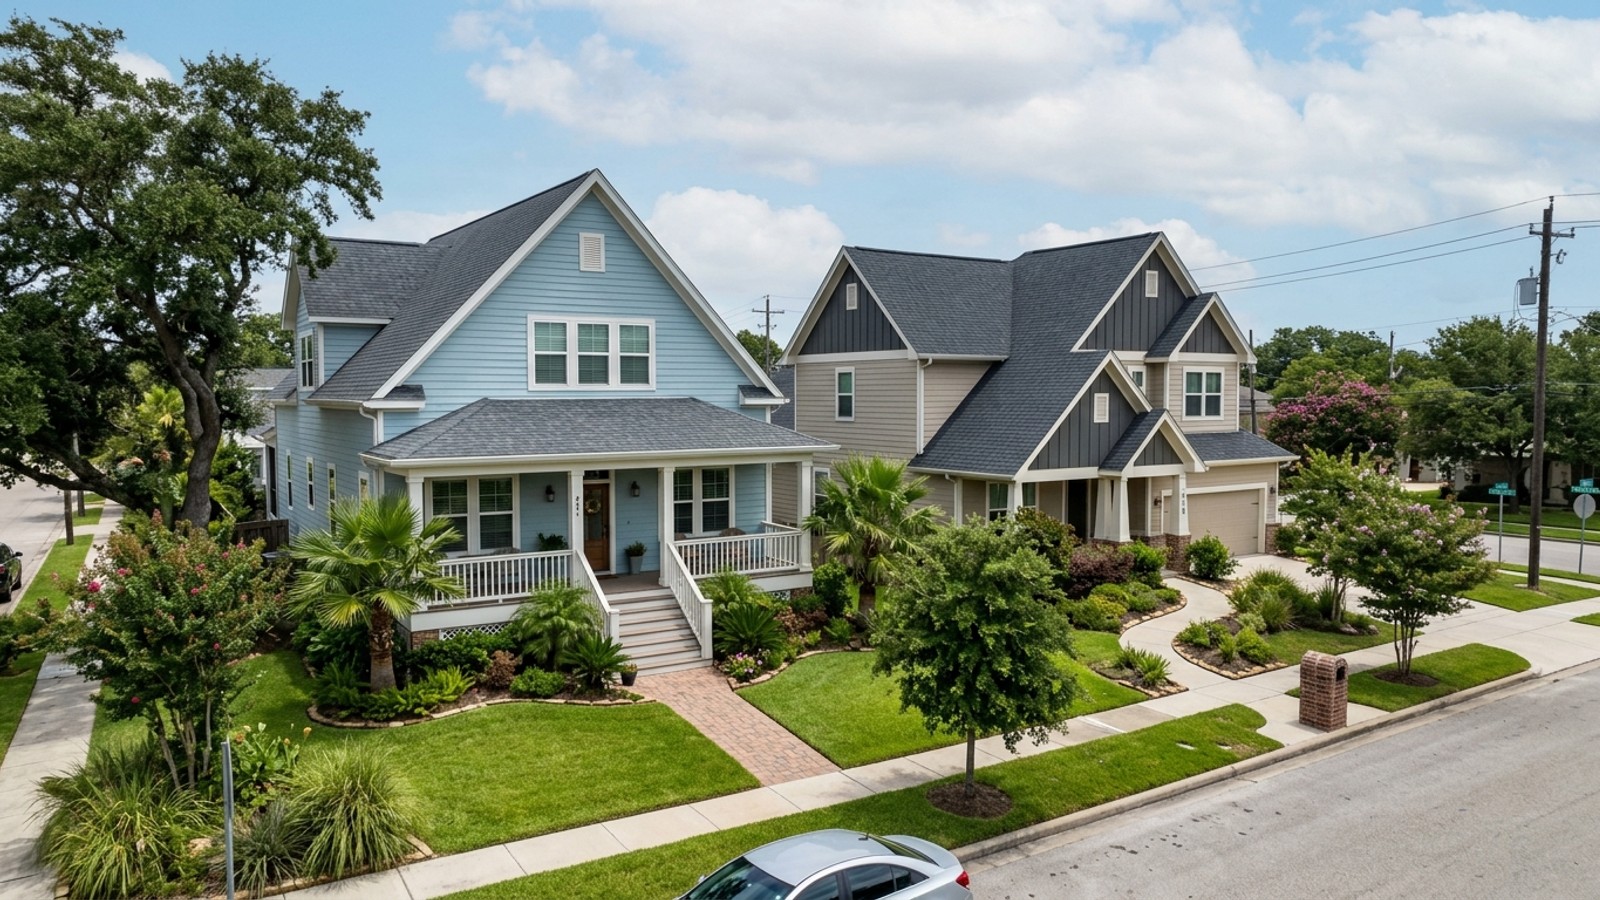
The median sale price for a home in Texas City, TX sits around $275,590. Homes are averaging about 72 days on market right now, which means you have some real time to think before you make an offer - that's not nothing. This timeline is especially helpful for first-time home buyers in Texas City, TX.
But sticker price is only the starting point. What you can actually afford depends on your monthly income, what you already owe, and some carrying costs that are specific to this part of the Gulf Coast - windstorm insurance and Galveston County property taxes being the two that catch buyers off guard most often.
Basic Affordability Rules for Texas City Buyers
Before a lender will approve your mortgage, they'll run your financial profile against specific debt-to-income benchmarks. Those benchmarks set the ceiling on your monthly payment. Understanding them before you start touring homes keeps you from falling in love with something you can't close on.
Online calculators can give you a rough idea, but what underwriters actually do is compare your gross monthly income against every recurring debt obligation you carry. It's a simple formula with real consequences.
The 28/36 Rule Explained
The 28/36 rule is the standard starting point financial professionals use. The idea is that your housing costs - principal, interest, taxes, and insurance combined - shouldn't exceed 28% of your gross monthly income.
The 36% side covers all of your debt together. So even if your housing payment stays under 28%, if car loans and credit cards push your total debt past 36% of gross income, lenders may cut your maximum loan amount. Both numbers matter.
Calculating Your Debt-to-Income Ratio
Your debt-to-income ratio - DTI - is the actual figure underwriters plug into their models. Divide your total minimum monthly debt payments by your gross monthly income and that's it.
Most conventional lenders want to see a DTI below 36%, though some government-backed loans will allow higher ratios. If you're carrying high-interest credit card balances, paying those down before you apply is one of the most direct ways to improve what you can borrow.
Carrying Costs in Galveston County
This is where buyers who move here from other parts of Texas sometimes get surprised. Total combined property tax bills in Galveston County generally range from 1.58% to 1.96% of a home's assessed value - that figure includes county, city, school, and special district taxes, and it varies depending on exactly where in Texas City the property sits.
Insurance is the other variable, and on the Gulf Coast it's a significant one. These two recurring costs can add hundreds of dollars to your monthly payment, which directly lowers the purchase price you can qualify for.
Local Property Taxes
Galveston County's median effective property tax rate falls between 1.19% and 1.38% - actually a bit lower than the Texas state median of 1.48%. Local school and municipal levies are what push the total bill up into that 1.58% to 1.96% range.
Lenders will require you to escrow taxes, so a portion of your annual bill gets folded into your monthly payment. Before you make an offer on anything, verify the specific rate that applies to that address. Municipal boundaries shift the final number more than most buyers expect.
Homeowners Insurance and Windstorm Coverage
According to the Texas Department of Insurance, the average annual homeowners premium statewide was about $3,291 in 2024. Consumer analyses for 2025 and 2026 show premiums frequently landing in the $4,000 to $4,900 range, particularly along the coast.
Texas City buyers typically need a separate windstorm policy on top of that to cover hurricane damage. Get insurance quotes early - before you're emotionally invested in a specific house - so you know whether those premiums fit the budget you've built.
Homeowners Association Fees
Newer developments and condo communities in Texas City often come with monthly HOA dues covering amenities, common area maintenance, and sometimes exterior repairs. What a lot of buyers don't realize until underwriting is that lenders include HOA fees in your DTI calculation. A $150 monthly fee sounds manageable, but it directly reduces how much principal and interest you can borrow.
How Local Home Prices Shape Your Budget
With a median home price around $275,590 and roughly 326 active listings, Texas City is a relatively accessible market compared to the broader Houston metro. Properties here sell for about 96% of list price on average, and there's around 4.7 months of supply - which puts it in balanced-market territory.
How far your budget stretches, though, depends on what type of property you're targeting and how much you're putting down.
Property Types and Price Differences
Single-family homes generally cost more upfront, but they often avoid the HOA fees that come with condos and townhomes. Townhomes sit in the middle - lower purchase prices paired with shared maintenance responsibilities.
Don't just compare purchase prices. A condo with a lower sticker price can end up costing you the same per month as a slightly more expensive single-family house once you factor in association dues. Run the full monthly cost for each property type before you decide what makes sense.
Down Payment Expectations
A larger down payment reduces your loan balance, lowers your monthly principal and interest, and - at 20% down on a conventional loan - eliminates private mortgage insurance entirely. That said, you don't need 20% to buy in Texas City.
Many loan programs allow down payments as low as 3% to 3.5%. You'll carry a higher monthly payment, but the door is open.
Loan Options and Down Payment Assistance
Texas City buyers have access to conventional loans, government-backed mortgages, and a handful of state-level programs that can meaningfully increase your purchasing power. Using one of these programs isn't a shortcut - it's just smart cash management that keeps more of your money available for closing costs and reserves.
Several state and regional agencies run programs specifically for first-time buyers in Galveston County, and the differences between them are worth understanding.
First-Time Buyer Programs in Texas
The Texas State Affordable Housing Corporation offers both the "Homes for Texas Heroes" and "Home Sweet Texas" programs, which provide grants or forgivable second liens worth 2% to 5% of the loan amount. You'll need a credit score of at least 620 to qualify.
The Texas Department of Housing and Community Affairs runs the "My First Texas Home" program, which offers up to 5% in assistance. You can also check Freddie Mac's DPA One platform to find local options, including the 5 Star Texas Advantage Program.
Loan Limits for FHA and VA Mortgages
For 2026, the FHA loan limit for a single-family home in Galveston County is $541,287. That limit comfortably covers Texas City's median price, so FHA financing is a realistic option for most buyers here.
VA loans - available to eligible military service members and veterans - allow zero down payment with no private mortgage insurance. For buyers who qualify, that's typically the most affordable path to ownership, full stop.
Frequently Asked Questions
What salary do I need to make to afford an average-priced home in Texas City, TX?
It depends on your existing debts and how much you're putting down. To afford the median $275,590 home while keeping your debt-to-income ratio below 36%, you need to balance your gross income against all your monthly obligations. A lender can run your exact numbers based on current interest rates - that conversation is free and worth having early.
How much do Texas City property taxes and windstorm insurance add to my monthly mortgage payment?
Enough to matter. Combined property taxes range from 1.58% to 1.96% of the home's value, and Texas homeowners insurance premiums frequently reach $4,000 to $4,900 annually - before you add separate windstorm coverage on top of that.
What down payment assistance programs can help me afford a house in Texas City?
The "Home Sweet Texas" and "Homes for Texas Heroes" programs offer grants up to 5% of the loan amount. The "My First Texas Home" program and the 5 Star Texas Advantage Program also provide local funding worth looking into.
Does buying in a Texas City flood zone lower the maximum mortgage amount I can get approved for?
Yes. Required flood insurance premiums count toward your monthly housing costs, which means they get factored into your DTI. That reduces how much principal and interest you can borrow.
What steps do I need to take to get an official mortgage pre-approval before house hunting in Texas City?
You'll need to submit a formal application so a lender can review your finances. The underwriter calculates your maximum monthly payment based on your gross income, existing debts, and the carrying costs specific to Galveston County.
With current local housing costs, is it more affordable to rent or buy in Texas City right now?
It depends on how long you plan to stay and how much cash you have available. Buying a median-priced $275,590 home requires upfront funds for a down payment and closing costs, but it locks in a stable principal and interest payment for the life of the loan. That stability has a value that renting doesn't.
April Aberle
REALTOR ® | Mortgage Originator | Homes for Heroes Affiliate | April Aberle | REMAX Crossroads Realty
or another way